
rapid! Pay
- Rating
- 4.3
- Downloads
- 1.00M
- Content Rating
- Everyone
rapid! Pay - Screenshots
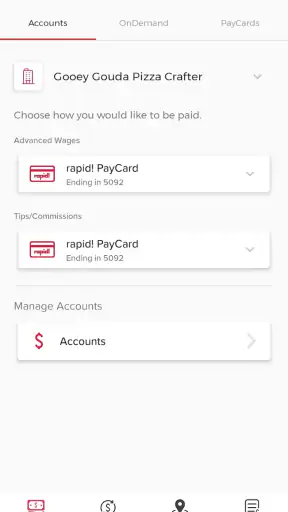
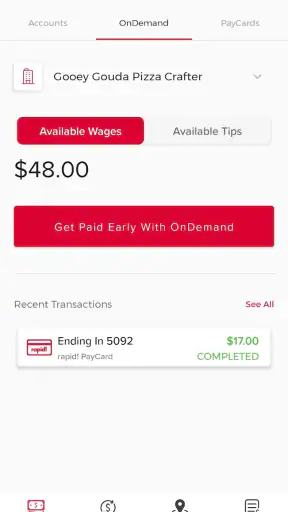
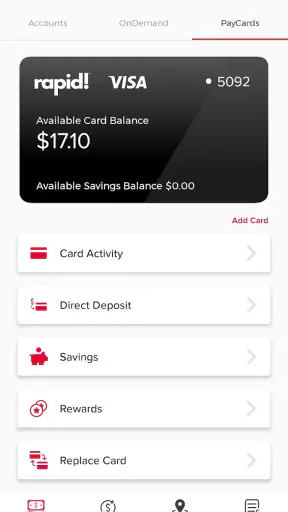
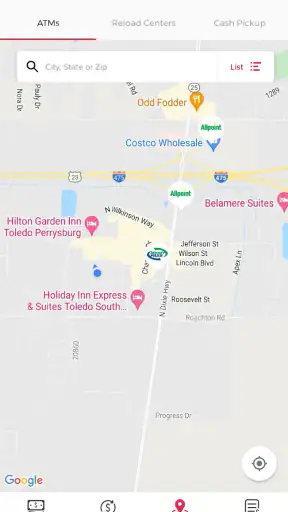
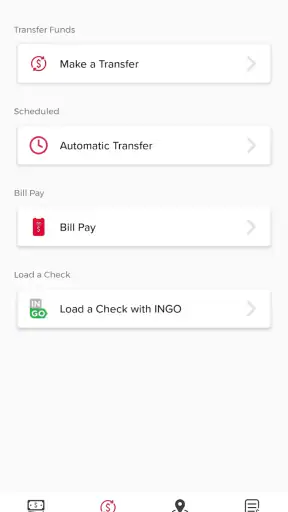
Pros
- Fast QR and contactless payments at participating stores.
- Supports multiple payment methods in one convenient wallet.
- Transaction history makes spending easier to monitor.
- Useful for splitting bills and sending money to contacts.
- Strong security features help protect payment information.
Cons
- Available only in selected countries and supported regions.
- Some merchants may not accept rapid! Pay yet.
- Identity verification can take time before full access is granted.
- Certain features may depend on your bank or card provider.
- Occasional app or payment issues may require retrying a transaction.
rapid! Pay - Description
- App Name
- rapid! Pay
- Package Name
- com.rapid.rapidpay
- Developer
- Green Dot
- Category
- Finance
- Last Updated
- Oct 30, 2020
- Version
- 1.0.116
Managing a payroll card from a phone sounds simple, but the quality of the experience depends on whether the app gives me the right information quickly and makes routine money tasks feel predictable. rapid! Pay is a finance app from Green Dot built for rapid! cardholders, and its main purpose is to put card access and account management in a mobile setting. I found it most relevant for people who already use a rapid! card and want a more convenient way to keep an eye on their money than relying on a physical card or occasional account checks.
The app is free to download, which makes trying it a low-risk decision for an existing cardholder. That does not mean every financial service connected with a card is automatically free, so I would still read the applicable account terms before assuming that every transaction or optional service costs nothing. The useful distinction here is straightforward: the app itself has no purchase price, while the value comes from how well it helps you manage the rapid! account you already use.
How rapid! Pay fits into everyday card management
rapid! Pay is not presented as a general-purpose banking replacement. Its identity is much narrower: it is the mobile companion for rapid! cardholders, with registration for new users and access intended for people using that card program. That focus is important. If you are searching for a broad budgeting tool, an investment platform, or a banking app that combines several unrelated financial products, this is probably not the right starting point.
For the intended audience, the appeal is convenience. A payroll card is something I would normally want to check around practical moments: before buying groceries, after receiving pay, when planning a bill payment, or when trying to understand whether a recent card purchase has gone through. A dedicated mobile app can make those checks feel less dependent on a computer or a call to support.
The app is listed for Everyone, and it supports devices running Android 7.0 or later. That gives it a relatively broad Android reach, although compatibility is not the same as a guarantee of an identical experience on every older phone. On an aging device, I would keep the operating system updated where possible and make sure the phone has enough free space for normal app updates.
Green Dot is the developer behind the app. Its presence on the major mobile ecosystem is substantial, with more than a million installs and an average rating of 4.3 from roughly seventy-eight thousand ratings. Those figures suggest that rapid! Pay is not a little-known experiment, but they should be read as a general signal rather than a promise that every cardholder will have the same experience.
Registration is the first important test
The first useful question for a new user is whether registration matches the card and personal details already associated with the rapid! account. I would approach setup carefully rather than rushing through it, especially when entering identifying information. A mismatch can turn a simple sign-up into a support issue, so using the same details connected to the card is a sensible first step.
Once access is established, I would spend a few minutes learning where the balance and account activity appear before depending on the app during a busy day. This is a small but practical habit: knowing where to look when you are standing at a checkout is more useful than discovering the layout while a payment is waiting.
Another good setup habit is to review the phone’s security basics. A screen lock, current operating system, and careful handling of login details matter more for a finance app than for a casual social application. I would avoid saving sensitive information in an unsecured note and would not hand an unlocked phone to someone while the account is open.
What value does the free app provide?
Because rapid! Pay is free to install, its value is measured in saved effort rather than a discount or a paid package of advanced tools. The strongest benefit is having a dedicated place to interact with a rapid! card account. For someone who receives wages through that card, quick access can make the account feel more usable between paydays.
A realistic example is a weekday grocery trip. I might check the available balance before leaving home, use the card at the store, and later open the app to review the account rather than trying to remember the exact amount spent. That workflow does not replace responsible budgeting, but it can reduce guesswork. It is especially helpful when several small purchases have happened since the last time I checked the account.
I also see value in using the app as a routine checkpoint instead of opening it only when something goes wrong. A short review after receiving pay, another before a large planned purchase, and a final check after recurring expenses can help me notice activity sooner. The app does not need to become a full budgeting system to support that habit.
One less obvious advantage of a card-specific app is reduced confusion. A general banking app may show checking accounts, savings, credit cards, transfers, and other products in one crowded interface. rapid! Pay has a more focused purpose, so a cardholder who only needs card-related access may find it easier to understand than a large financial dashboard.
That focus is also the main trade-off. A narrow app is useful when it matches my needs, but it will not suddenly become a complete replacement for every financial tool I use. I would still expect to use a separate service for detailed spending categories, long-term savings goals, investment tracking, or managing accounts outside the rapid! card relationship.
Practical habits that make the app more useful
My first tip is to check the balance before making a payment that matters, not only after the transaction. This creates a simple reference point. If the amount later looks different, I have a clearer idea of when the change occurred. It is a basic workflow, but it is more reliable than trying to reconstruct spending from memory.
My second tip is to use the app at consistent moments rather than repeatedly refreshing it throughout the day. A morning check before commuting and an evening review after purchases can be enough for many people. Constant checking can create unnecessary anxiety, while never checking means an unexpected issue may go unnoticed longer.
My third tip is to treat the app as one part of a money routine. I would pair it with a simple note or budget elsewhere if I needed to plan bills, because seeing a balance is not the same as knowing how much of that balance is already committed. For example, money needed for rent or utilities should not be treated as freely available just because it appears in the account.
A fourth useful habit is to keep support information accessible without storing private credentials in plain text. If registration or account access becomes difficult, having the cardholder details and official account information ready can make the next step smoother. I would never send a full password or sensitive card information through an informal message.
Where the experience may feel limited
The biggest limitation is the app’s narrow role. A user who wants detailed financial analysis may find the experience too basic, even if it handles card access well. I would not choose rapid! Pay as my only financial app if I needed a complete household budget, shared expense planning, debt tracking, or a consolidated view of several banks.
There is also a difference between mobile convenience and financial control. An app can make account information easier to reach, but it cannot solve poor spending timing or replace a plan for upcoming bills. Someone who tends to spend based on the visible balance alone may need a separate budgeting method alongside it.
Registration can be another point of friction for new users. Card-linked financial apps need accurate identity and account matching, and that can feel less immediate than signing up for an ordinary entertainment app. I consider that a reasonable security-related inconvenience, but it still affects how quickly a new cardholder can get started.
Older Android users should also be realistic about device compatibility. The minimum operating system is Android 7.0, so phones below that threshold are not suitable for the current app requirement. Even on a supported phone, an older device may make sign-in, updates, or general navigation less comfortable than on newer hardware.
Finally, I would not assume that the absence of an app purchase price means the entire card relationship is cost-free. The app is free, but financial products can have their own terms, transaction rules, or service conditions. Before relying on a particular way of accessing or moving money, I would check the current rapid! account documentation rather than making a decision from the download price alone.
Who is most likely to benefit?
rapid! Pay makes the most sense for an existing rapid! cardholder who wants mobile access during ordinary daily spending. It is particularly suitable for someone who checks a payroll card regularly, prefers a phone over a desktop browser, and wants a focused account companion rather than a large banking suite.
It may also suit a new cardholder who wants to register and establish a regular checking routine. In that situation, the app can become a practical part of payday planning: confirm the account, review available money, identify upcoming obligations, and avoid treating the entire balance as disposable.
I would be more cautious recommending it to someone choosing a financial product from scratch. If your priority is a traditional bank relationship, extensive budgeting, savings tools, or access to several account types in one place, compare those alternatives before deciding. A free app is not automatically better than a service with a broader feature set if your financial needs are broader too.
It is also not the ideal choice for people who rarely use smartphones or who are uncomfortable managing sensitive accounts on a mobile device. In that case, another access method may feel more dependable. The best app is the one you can use confidently and securely, not merely the one with the largest install number.
How it compares with usual finance alternatives
Compared with a general banking app, rapid! Pay appears more specialized. A traditional bank application usually makes sense when I need checking, savings, transfers, statements, and multiple products under one login. rapid! Pay is more appealing when the rapid! card is the center of my financial activity and I do not want unrelated features competing for attention.
Compared with a budgeting app, the difference is even clearer. Budgeting software is designed around categories, goals, forecasts, and spending plans. rapid! Pay is better understood as an access and account-management tool for the cardholder. I would use the two together if I wanted both a current account view and a more deliberate plan for where my money should go.
Compared with relying on a physical card alone, the mobile app offers a more convenient way to stay informed. The physical card remains useful for payments, but it cannot provide the same at-a-glance account routine. The trade-off is that mobile access brings extra responsibility: I need to protect the phone and login just as carefully as I protect the card.
The app’s current version is 1.0.116, and the listing shows an original release date of October 30, 2020. I treat the version number mainly as an identification detail rather than a reason to expect a particular feature set. What matters in daily use is whether the installed build works properly on my phone and supports the account tasks I actually need.
My verdict on downloading rapid! Pay
I would recommend rapid! Pay to a rapid! cardholder who wants a free, focused mobile companion and is prepared to keep a separate method for broader budgeting. Its strongest quality is practical access: the app puts card management closer to the moments when I need it, such as checking funds before shopping or reviewing activity after a busy day.
I would skip it as a primary finance solution if I needed a full-service banking platform, detailed financial planning, or one dashboard for several unrelated accounts. In that situation, a conventional banking app or dedicated budget tool would offer a better match, even if its scope were wider and its interface less focused.
Overall, rapid! Pay delivers sensible value for its intended audience because the download is free and the purpose is clear. The important decision is not whether the app costs money to install; it is whether a rapid! card is already part of your financial routine. If it is, I think the app is worth trying, provided you set it up carefully, protect your access, and remember that mobile convenience works best when it supports a budget rather than replacing one.
With an Everyone age rating, support for Android 7.0 and later, and a substantial user base, it is accessible to many Android cardholders. My final recommendation is therefore conditional but positive: choose it for focused rapid! card access, use it as a regular account-checking tool, and look elsewhere when your needs extend into full banking or serious financial planning. That is where its free price feels genuinely useful—and where its limits become clear.
FAQ
What is rapid! Pay, and what can I use it for?
rapid! Pay is a mobile payment and money-management app designed for users who receive payments through the rapid! payroll card program. After installing the app, you can typically check your available balance, review recent transactions, locate surcharge-free ATMs, and manage selected card settings from your phone. Its usefulness depends on whether your employer or card issuer supports rapid! services, so check your card details and eligibility before downloading.
Is rapid! Pay safe to use for checking my balance and managing my card?
The app is intended to provide secure access to rapid! card information through account authentication and device-based security features. During our review, the most important protection came from using a strong login, keeping the app updated, and avoiding public Wi-Fi when entering sensitive details. No financial app is completely risk-free, so users should never share passwords, verification codes, card numbers, or login information with anyone.
Can I use rapid! Pay to transfer money or deposit checks?
Available services can vary according to your rapid! card, employer program, account status, and the app version installed on your device. Some users may have access to features such as direct-deposit information, transfers, mobile check deposit, or card-to-card payments, while others may only see balance and transaction tools. Review the features shown for your account after signing in, and confirm fees, limits, and processing times before initiating a transaction.
Are there fees for using rapid! Pay or withdrawing money?
Downloading and using the rapid! Pay app may not involve a separate subscription cost, but individual financial services can still carry fees. ATM withdrawals, out-of-network transactions, expedited services, replacement cards, or certain transfer options may be charged depending on your card agreement. The app or its terms should display applicable charges, so read the fee schedule carefully rather than assuming every feature is free.
What should I do if I cannot log in, lose my card, or notice an unauthorized transaction?
If you cannot access rapid! Pay, use the in-app recovery or support options and verify that your phone number, email address, and app version are current. A lost or stolen card should be reported immediately through the official support channel so it can be locked or replaced. For an unfamiliar transaction, contact card support promptly, change your credentials, and avoid relying on unofficial websites or phone numbers.


